What is the Carbon Management System Market definition, scope, and industry significance?
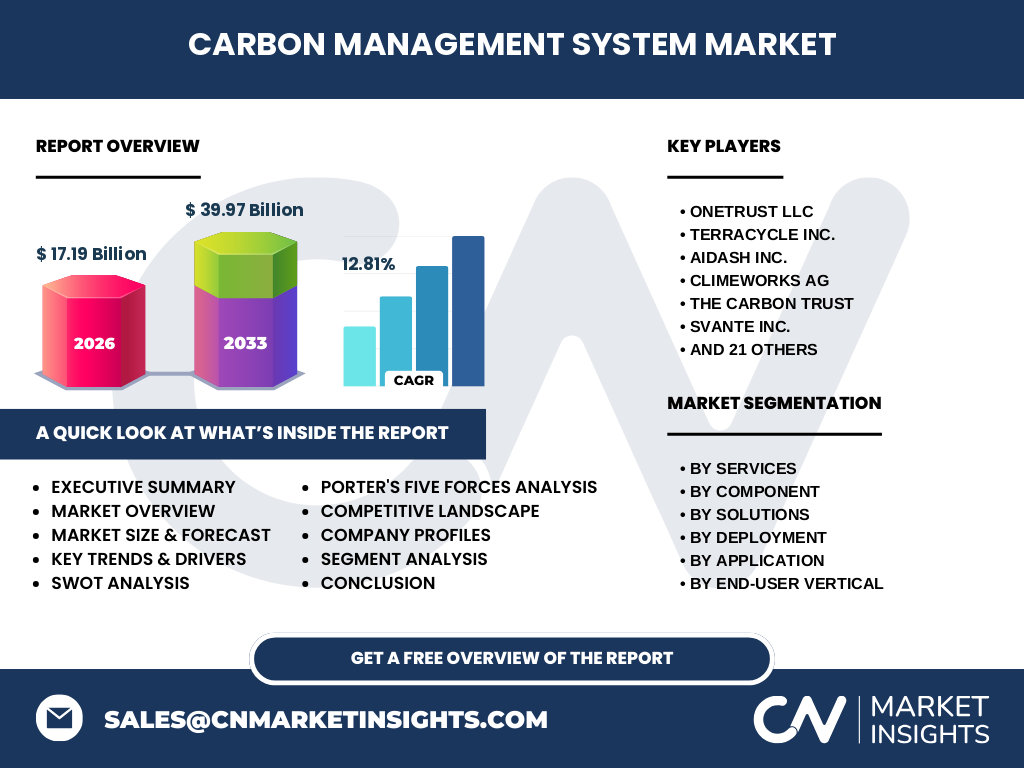
Our analysis indicates that the Carbon Management System Market represents a critical enterprise software and services sector valued at 17.19 Billion in 2026. This ecosystem enables heavy emitters in oil and gas, manufacturing, and utilities to track scope 1, 2, and 3 emissions, ensuring compliance with evolving standards from regulatory bodies like the SEC and European Union.
Structural Growth Drivers, Restraints, and Opportunities
The market is propelled by stringent decarbonization mandates enforced by the EPA and EU CSRD, alongside corporate net-zero commitments. However, high implementation costs and fragmented emissions data silos act as structural restraints. Growth opportunities thrive in automated AI-driven carbon accounting platforms provided by innovators like Plan A UG and Carbmee Technologies Pvt. Ltd.
Emerging Trends and Growth Patterns in Carbon Management System Market
Recent industry trends highlight a decisive shift toward real-time emissions monitoring and blockchain-verified carbon offsetting. Enterprises are moving away from manual spreadsheets toward automated SaaS modules. This benefits specialized players like CarbonChain Limited and WattTime Corporation, which integrate grid-level carbon intensity data directly into enterprise resource planning software.
How did COVID-19 impact the Carbon Management System Market recovery trajectory?
The pandemic temporarily disrupted enterprise software budgets, yet it ultimately accelerated digital transformation and sustainability reporting integration. Supply chain vulnerabilities forced organizations to adopt cloud-based carbon management architectures. Consequently, the sector rebounded sharply, paving the way for a projected market valuation of 39.97 Billion by 2033.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately fragmented, featuring a mix of enterprise ESG software giants and specialized climate-tech disruptors. Strategic dynamics focus on M&A activity and API integrations. Companies such as OneTrust LLC and The Carbon Trust dominate compliance advisory, while agile startups focus on automated carbon footprint and data analytics optimization.
Executive Summary of the Carbon Management System Market
Driven by a robust 12.81% CAGR spanning 2027 to 2033, the market is scaling from its 2026 baseline of 17.19 Billion to reach 39.97 Billion by the end of the forecast period. Regulatory pressure and mandatory disclosure laws are transforming carbon management from a voluntary corporate social responsibility initiative into an essential core financial process.
Long-Term Market Forecast from 2027 to 2033
Based on our econometric modeling, the Carbon Management System Market market size will expand rapidly at a 12.81% CAGR between 2027 and 2033. The total addressable market will surge from 17.19 Billion in 2026 to peak at 39.97 Billion by 2033, fueled by widespread adoption across heavy industry end-users.
Granular Segmentation Analysis
The market is segmented by components (Solutions and Services), deployment (Cloud and On-Premises), applications (Energy, Greenhouse Gas Management, Air Quality Management, Sustainability), and end-user verticals (Oil and Gas, Manufacturing, Healthcare, IT and Telecom). Services encompass Consulting, Implementation, Training, Managed, and Audit and Compliance Services, supporting complex deployment strategies.
Geographic Distribution and Regional Performance
Geographic performance is led by North America and Europe, where regulatory frameworks like the Corporate Sustainability Reporting Directive mandate rigorous greenhouse gas disclosures. Meanwhile, Asia-Pacific represents the fastest-growing frontier due to rapid industrialization in manufacturing hubs and tightening environmental standards enforced by regional authorities.
In-Depth Regional Review and Localization Constraints
North America benefits from early enterprise software adoption and stringent SEC climate disclosure proposals. In contrast, the European market prioritizes auditable supply chain emissions tracking, boosting demand for solutions offered by CarbonCloud AB. Localization constraints involve navigating disparate carbon pricing mechanisms across international jurisdictions.
Company Profiles and Strategic Positioning
Leading industry participants occupy distinct operational niches. Climeworks AG and Svante Inc. pioneer carbon dioxide removal technologies, while Pachama Inc. and NCX dominate satellite-verified forest carbon credits. Software innovators like LogicLadder Technologies Pvt. Ltd. and AiDash Inc. provide specialized industrial emissions tracking.
Porter's Five Forces Analysis of the Sector
Bargaining power of buyers is moderate to high due to numerous ESG software vendors, while supplier power remains low given the commoditized nature of cloud infrastructure. Threat of substitutes is minimal because regulatory reporting mandates specialized compliance architecture. Competitive rivalry is intense, driving continuous AI and automation feature rollouts.
SWOT Analysis of Carbon Management System Market
Key strengths include high regulatory compliance demand and advanced SaaS scalability. Weaknesses involve data integration hurdles across legacy ERP systems. Opportunities lie in expanding carbon credit exchange platforms like AirCarbon Exchange (ACX). Threats stem from potential data privacy regulations and shifting political mandates.
Value Chain Analysis and Industry Structure
The value chain flows from raw IoT sensor data collection and satellite earth observation providers through core software analytics engines to enterprise reporting dashboards. Value capture concentrates heavily on proprietary emissions accounting software and verified offset advisory services delivered by firms like TerraPass Inc. and Verdani Partners LLC.
Investment Insights and High-Potential Areas
Venture capital and private equity investors should prioritize Carbon Management System Market industry trends favoring automated Scope 3 supply chain tracking and Scope 1 real-time IoT emissions monitoring. High-potential areas include integrated solutions for manufacturing and oil and gas sectors seeking seamless auditing tools.
Conclusion and Strategic Takeaways
The Carbon Management System Market analysis confirms that transitioning to automated carbon tracking is no longer optional for global enterprises. With the market scaling from 17.19 Billion in 2026 to 39.97 Billion by 2033, early adopters of cloud-based emissions accounting will secure distinct regulatory and operational advantages.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary executive interviews with Chief Sustainability Officers, and secondary macroeconomic indicators. We cross-reference corporate ESG disclosures with software licensing metrics to project the 12.81% CAGR through 2033.
Scope of the Report and Coverage Parameters
This research report evaluates global deployment trends, component categories, and end-user verticals across North America, Europe, Asia-Pacific, and Rest of World. Limitations include rapid regulatory policy shifts and the voluntary nature of certain carbon offset standards, which may impact near-term software adoption rates.
Recent Developments and Strategic Industry Moves
Recent market activity is characterized by strategic partnerships between carbon accounting software providers and major carbon exchanges. Announcements from firms like CarbonCure Technologies Inc. and Carbon Clean Solutions Limited highlight ongoing R&D investments in industrial carbon capture integration and verified blockchain offset trading.